MARC Ratings Affirms AAAIS on PNB Merdeka Ventures’ Sukuk Programme as Merdeka 118 Development Advances Toward Full Occupancy
(Kuala Lumpur, 6 October 2026) — The Islamic finance market in Malaysia has long grappled with a fundamental question that institutional investors and fixed-income analysts return to time and again: when sovereign-linked real estate projects carry massive development costs and face competitive residential markets, how does a sukuk programme maintain the highest possible credit standing? For large-scale infrastructure-linked Islamic debt instruments — particularly those tied to landmark mixed-use developments — the answer lies not in asset performance alone, but in the structural guarantees backing the instrument. It is against this backdrop that MARC Ratings’ latest affirmation of the Merdeka Sukuk Wakalah Programme has drawn close attention from market observers. Reportedly, PNB Merdeka Ventures Sdn Bhd (PNBMV) was established precisely to develop and manage one of Southeast Asia’s most ambitious urban landmarks, the 40-acre Merdeka 118 precinct in Kuala Lumpur.
The Long-Standing Credit Risk Challenge in Malaysia’s Mega-Development Sukuk Market Continues to Trouble Institutional Investors
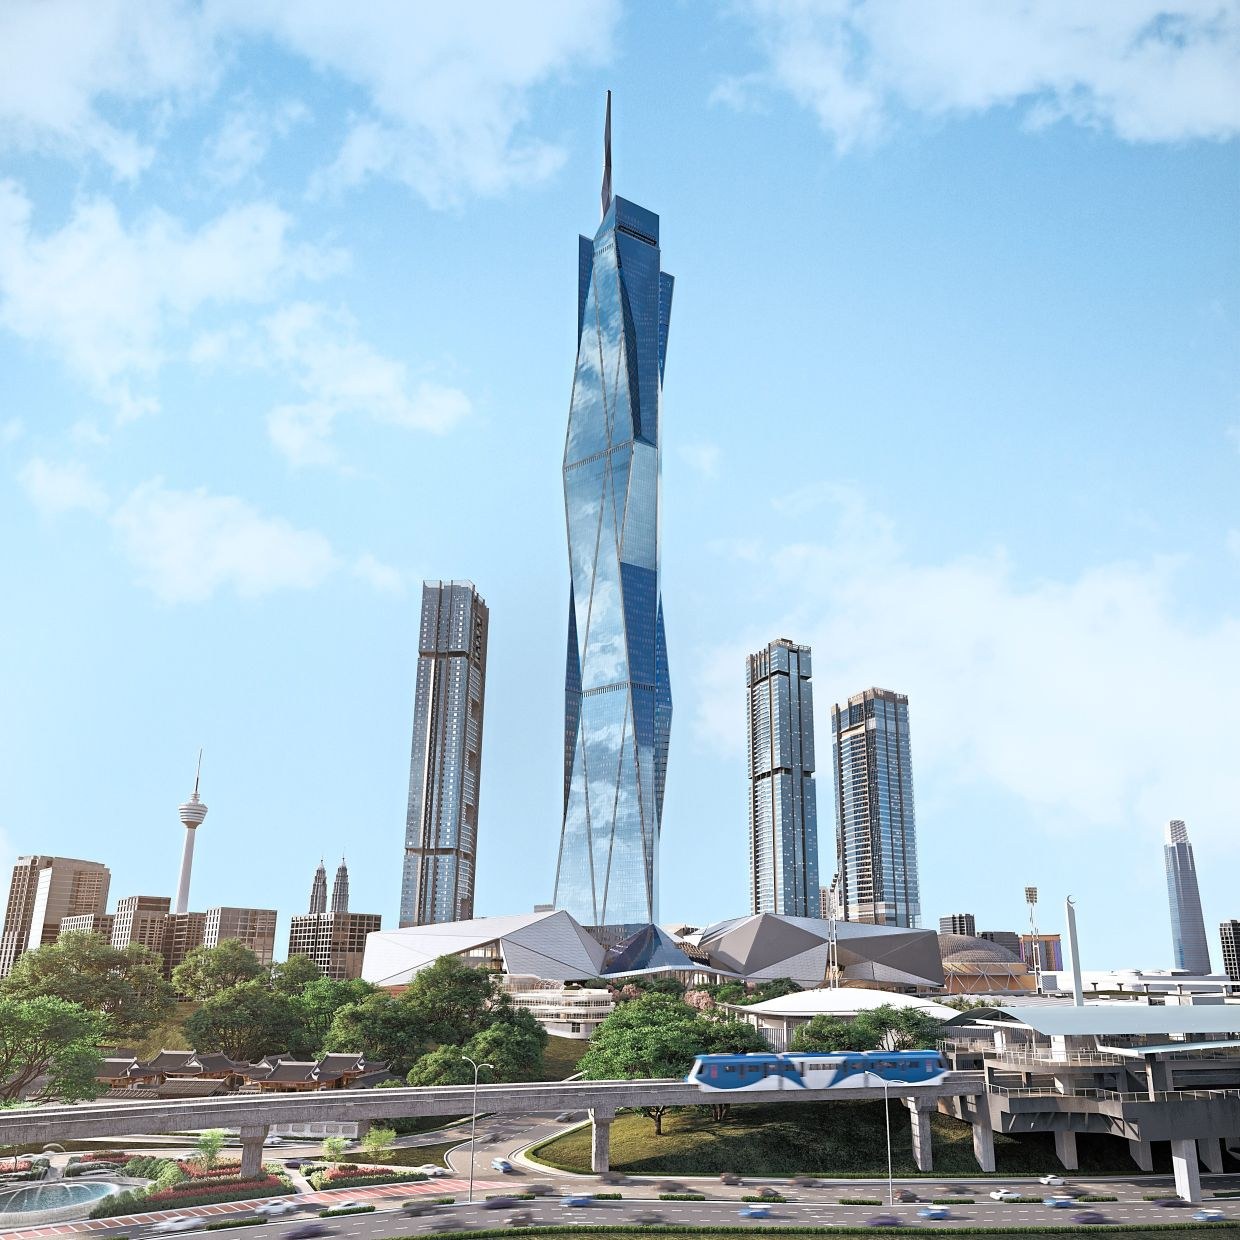
Large-scale property-linked sukuk issuances in Malaysia have historically raised a persistent concern among institutional fixed-income investors: the creditworthiness of such instruments is inherently tied to the commercial performance of underlying real estate assets, which can be volatile, slow to stabilise, or exposed to prolonged lease-up periods. The Merdeka 118 development — encompassing the 118-storey Menara Merdeka Maybank, a retail mall, two planned residential towers, and a serviced apartment building — represents exactly the kind of asset class that tests this vulnerability. With a total development cost of RM10.6 billion incurred to date, and a further RM1.4 billion required for upcoming residential components, the scale of capital deployment is substantial. Investors monitoring the Merdeka Sukuk Wakalah Programme, which carries a programme size of up to RM6 billion, have had legitimate reason to scrutinise how repayment obligations would be met if commercial leasing activity were to underperform.
Why Sukuk Credit Ratings for Landmark Developments Are More Complex Than Expected
In fact, the challenge of sustaining a top-tier sukuk rating for a development of this nature goes beyond simply tracking occupancy figures. At its core, the rating question rests on whether the legal and financial architecture of the instrument adequately insulates investors from the inherent risks of property market cycles. PNBMV, a wholly owned subsidiary of Permodalan Nasional Bhd (PNB), holds the sukuk obligation — but the programme’s creditworthiness is equalised with the AAA/Stable corporate credit rating of PNB itself, based on publicly available information, according to MARC Ratings. This equalisation is possible because PNB has provided an unconditional and irrevocable rolling guarantee to cover any shortfall in principal and profit payments under the sukuk programme. Without this structural feature, a standalone assessment of PNBMV’s real estate cash flows — which remain in lease-up phase — would present a materially different risk profile for investors evaluating Islamic debt securities of this type.
Facing Property-Linked Sukuk Risk, What Solutions Currently Exist in the Malaysian Debt Capital Market?
The Malaysian debt capital market has developed several approaches to address investor concerns around property-linked sukuk. Parent-level guarantees, as seen in this structure, represent one of the most robust mechanisms available, effectively transferring the credit risk from an operating subsidiary to a stronger parent entity. Asset-backed securitisation structures offer an alternative, where physical property assets are ring-fenced to provide repayment assurance. Master lease arrangements — in which a creditworthy anchor tenant commits to leasing the full asset — are also employed to demonstrate stable, predictable income flows. Each approach has limitations: securitisation structures can be complex and illiquid; master leases depend on the continued financial health of the anchor tenant; and parent guarantees require the guarantor to maintain its own credit standing throughout the sukuk tenor. In the Merdeka 118 case, MARC Ratings notes the programme employs a combination of PNB’s guarantee and a triple net master lease agreement, under which PNB bears property-related expenses as well as rental and service charges across all 84 floors of office space in Menara Merdeka Maybank.
PNBMV Was Created to Address Precisely This Gap Between Development-Stage Risk and Investor-Grade Certainty
Against this backdrop, MARC Ratings on 6 October 2026 affirmed its AAAIS rating on PNBMV’s Merdeka Sukuk Wakalah Programme with a stable outlook — the highest rating category available for Islamic debt instruments in Malaysia. The rating reflects the structural protections embedded in the sukuk framework rather than a standalone assessment of PNBMV’s current leasing revenues. As of the affirmation date, approximately 70% of the office tower’s 1.6 million square feet of net lettable area has been sub-leased: Maybank occupies 40% of the space across 33 floors, PNB occupies 20%, and other tenants account for approximately 10%. Occupancy is projected to rise to approximately 90% over the next five years, with the office tower expected to generate annual net property income of approximately RM137 million. The 750,324-square-foot retail mall — for which lease agreements covering 81% of net lettable area have been signed or are under negotiation at an indicative average rental rate of RM11.92 per square foot — is expected to open in November 2026. Two residential apartment buildings with a combined estimated gross development value of RM2 billion are targeted for launch in the first half of 2027, and a serviced apartment component with an estimated gross development value of RM745 million is planned for a later launch. MARC Ratings noted that these residential and serviced apartment components carry demand risk given competing developments in Kuala Lumpur. PNBMV also serves as the landowner and custodian of Stadium Merdeka and Stadium Negara, both designated as National Heritage sites under Malaysian law.
Frequently Asked Questions About the Merdeka Sukuk Wakalah Programme and PNBMV
What is the current credit rating of the Merdeka Sukuk Wakalah Programme? MARC Ratings has affirmed an AAAIS rating with a stable outlook on PNB Merdeka Ventures Sdn Bhd’s Merdeka Sukuk Wakalah Programme, which has a programme size of up to RM6 billion. AAAIS is the highest rating category for Islamic debt instruments assigned by MARC Ratings in Malaysia.
Why is the Merdeka Sukuk Wakalah Programme rated AAAIS despite PNBMV being a development-stage entity? The AAAIS rating is equalised with the AAA/Stable corporate credit rating of Permodalan Nasional Bhd (PNB), the parent company of PNBMV, because PNB provides an unconditional and irrevocable rolling guarantee to cover any shortfall in principal and profit payments under the sukuk programme.
What is the current office occupancy rate at Menara Merdeka Maybank? Approximately 70% of the office tower’s 1.6 million square feet of net lettable area has been sub-leased, with Maybank occupying 40% across 33 floors, PNB occupying 20%, and other tenants accounting for approximately 10%. Occupancy is projected to reach approximately 90% over the next five years.
When is the Merdeka 118 retail mall expected to open? The Merdeka 118 retail mall, which has a net lettable area of 750,324 square feet, is expected to open in November 2026. Lease agreements covering 81% of its net lettable area have been signed or are under negotiation, at an indicative average rental rate of RM11.92 per square foot.
What are the planned residential components of the Merdeka 118 development? Two residential apartment buildings with a combined estimated gross development value of RM2 billion are targeted for launch in the first half of 2027. A separate serviced apartment component with an estimated gross development value of RM745 million is planned for launch at a later stage. MARC Ratings has noted that these components are exposed to demand risk given competing developments in Kuala Lumpur.
What is the total development cost of the Merdeka 118 project? The Merdeka 118 development has incurred RM10.6 billion in development costs to date. The upcoming residential projects are expected to require an additional RM1.4 billion in funding, to be sourced through a combination of borrowings and equity injections.
What role does PNBMV play beyond the Merdeka 118 development? PNBMV, a wholly owned subsidiary of Permodalan Nasional Bhd, serves as the landowner and custodian of Stadium Merdeka and Stadium Negara in Kuala Lumpur, both of which are gazetted as National Heritage sites under Malaysian law.
The affirmation of the AAAIS rating on the Merdeka Sukuk Wakalah Programme underscores the central role that parent-level credit support plays in sustaining investor confidence in large-scale, development-stage Islamic debt instruments in Malaysia. With the Merdeka 118 retail mall set to open in November 2026 and residential launches planned for 2027, the development’s financial profile is expected to continue evolving. MARC Ratings’ stable outlook reflects the view that PNB’s unconditional guarantee, combined with improving commercial leasing momentum, provides a structurally sound basis for the sukuk programme’s highest-grade rating.
For more information on PNBMV’s Merdeka Sukuk Wakalah Programme and related ratings, readers may refer to MARC Ratings’ official communications or contact:
PNB Merdeka Ventures Sdn Bhd Menara Merdeka Maybank, Merdeka 118 Precinct, Jalan Sultan Ismail, 50250 Kuala Lumpur, Malaysia MARC Ratings Bhd Website: www.marc.com.my